BAN PAYDAY
LOANS. — India Public Awareness Guide on Predatory 7–35 Day Loan Apps, 540.7% APR Debt Traps, RBI Digital Lending Rules & Borrower Legal Rights
STOP EXPLOITING PEOPLE WHO NEED MONEY.
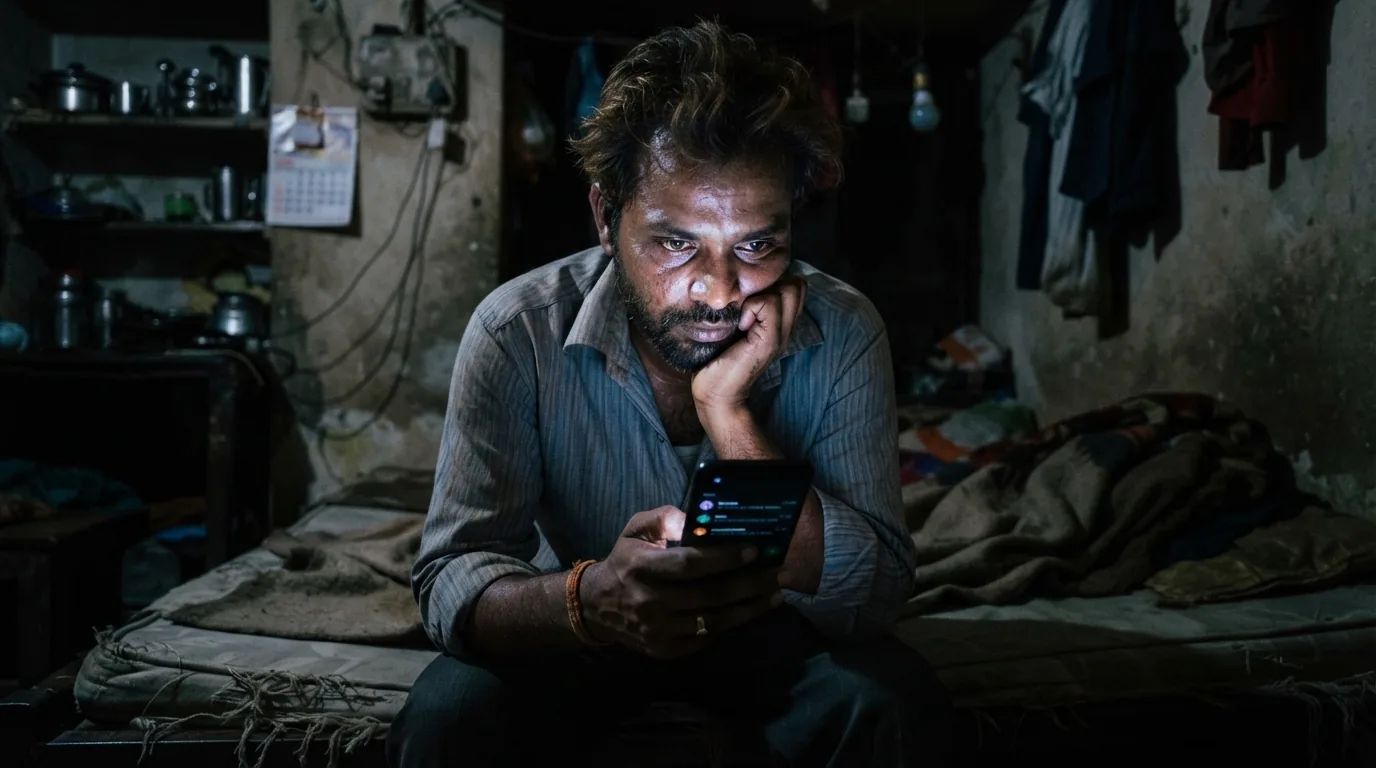
When sudden expenses hit, 7 to 35-day loan apps and instant web links promise instant cash—but a 10% upfront fee cut and 1% daily interest quickly trap borrowers in high-cost rollover cycles.
Across India, predatory mobile applications and browser web portals market "instant cash" with short 7 to 35-day tenures to working families facing emergencies. Behind the marketing lies a high-cost trap: a 10% upfront processing fee deduction, 1% daily interest (365% APR), and aggressive collection tactics when repayment comes due.
What a payday loan is — and why you must never take one
Unlike a bank EMI loan (6–36 months at 12%–24%/year), a payday loan is a 7 to 35-day cash advance via mobile browser WebApps. They cut 10%–32% upfront and charge ~1% every single day (540%–2,300%+ APR).
It doesn't solve an emergency — it turns a ₹30,000 shortage into ₹1,00,000+ debt in weeks. Worse, your bank statement / Account Aggregator feed exposes family UPI transfers & HR details that agents use to harass you. Asking family, HR advance, gold loan, or paying a bill late is always safer.
Ads promise "15%–35% APR & 61–365 day EMI." Those website tables are pure bait. Once you finish KYC inside the WebApp, the long tenure vanishes and you are pushed into a forced 7–14 day lump-sum loan.
You receive ₹26,400 in hand on a ₹30,000 loan and owe ₹33,000–₹39,000 within weeks. Your salary can't cover rent + the full lump sum, so out of panic you open WebApp #2 to pay #1 — then #3, #4, #5. Soon you pay ₹500–₹2,000/day in fees alone without clearing the loan. The only exit is stopping new loans today.
- • Engineered to fail: Profits depend on rollovers, penalty loops, and panic — not fair credit.
- • Destroys jobs, families & lives: Illegal family/HR shaming, fake police notices, and extortion threats have caused job losses and documented suicides across India.
- • Abuses regulatory loopholes: Uses RBI-registered NBFC cover and browser WebApps to bypass Play Store bans with fake website claims.
- • Zero social value: Ultra-short daily-interest payday loans cannot be fixed — they must be banned outright by law.
Break the chain of payday loans.
DON'T BORROW A NEW LOAN TO REPAY AN OLD ONE.
The 6 stages of the debt trap
The predatory digital lending apparatus is not standard credit. It is an engineered cycle built around planned delinquency and repeat borrowing.
Most lenders operate as mobile browser WebApps via Instagram, Facebook, and SMS links (not Play Store apps) to evade Google Play restrictions.
Most lending sites publish false rate tables showing 90-day EMIs and low APR purely as bait. Once you enter KYC on the WebApp, they disburse a predatory 7-day loan at 540%–2,300%+ APR. Under CPA 2019 Sec 2(28), this bait-and-switch is an illegal Unfair Trade Practice.
When sanctioned for ₹40,000, 10% (₹4,000) is deducted upfront as processing fees. You only receive ₹36,000 in your bank account.
The app or web portal charges 1% daily interest (₹400/day). In 30 days, interest is ₹12,000. Combined with the ₹4,000 fee, you pay ₹16,000 on ₹36,000 received. Under RBI rules including fees, this is an all-inclusive 540.7% APR (spiking to 984.9% on 7-day terms).
Predatory Usury Alert: Paying ₹16,000 extra on ₹36,000 cash received over 30 days equals 540.7% true APR (22.5x a typical 24% NBFC personal loan).
Short deadlines arrive before monthly finances recover. Automated dialers begin pressure messages days before the due date.
Lenders flood WhatsApp and email with friendly "Pre-Closure Offers" promising "2-minute reloans", "70% fee discounts", and fake "20-point CIBIL boosts".
Agents weaponize harvested contacts—either extracted via app permissions or demanded as mandatory emergency family references on web forms—to harass relatives and colleagues.
Agents send SMS/WhatsApp links to new web portals or sister apps to borrow again, doubling your fees and restarting the 1% daily interest clock.
Share awareness resources
SILENCE PROTECTS THE PROBLEM. AWARENESS BREAKS IT.
Predatory lenders rely on their targets feeling isolated and ashamed. Sharing clear legal guidance arms borrowers with immediate protection.
NEEDING MONEY IS NOT A CRIME. EXPLOITING IT IS.
Borrowing money does not cancel human dignity or privacy. Stand against illegal harassment, extortion, and unapproved web portals.
Key reforms needed
ENOUGH IS ENOUGH. THIS IS WHAT MUST CHANGE.
Ban predatory 7–35 day loans
Impose strict caps against 1% daily interest, ban deceptive 10% fee deductions, and enact a universal 36% APR statutory ceiling.
Penalties for contact scraping
Mandate criminal liability for companies whose software scrapes borrower contacts or sends unauthorized mass messages.
Enforce calling hours & ethics
Strict enforcement of permitted recovery hours (08:00–19:00) with automatic license revocation for abusive language or calling family members.
Single-page key fact statements
Mandate clear single-page disclosures showing net disbursed cash vs gross repayment amounts before any loan can be accepted.
Why we exist & our mission
"Because needing emergency money should never mean losing your dignity or privacy."
People who borrow money deserve basic respect and fair treatment, regardless of their financial circumstances.
A family's temporary hardship must never be weaponized to trap them in compounding interest or extortion.
Owing money does not give anyone the right to harass your family, message your contacts, or ruin your privacy.
When borrowers understand statutory protections and complaint channels, abusive recovery tactics lose their power.
Submit case evidence or contact us directly
We run no backend form on this site. Share your loan app/WebApp experience or reach out for help via Google Form or Email: